A Market Adjusting to “Higher for Longer”
Mortgage rates have been staying around the 6 percent range for most of 2026. The latest survey from Freddie Mac says that the average rate for a 30years fixed mortgage is 6.65 percent as of August 20. This is a little lower than the week before when it was 6.67 percent. If we look back at the time last year the rate was 6.58 percent. So, this is not a short-term problem that buyers are waiting to go away. Mortgage rates are pretty much where they are going to stay. This is affecting who is buying houses, who is waiting to buy and how people are pricing and negotiating homes in Palm Beach County right now. Mortgage rates are really shaping the way the housing market is working. People are looking at mortgage rates. Deciding what to do about buying a home, in Palm Beach County.
Locally the numbers show a market that is slowing down from the speed it had during the pandemic. Is still keeping its value. According to Momentum Realty’s tracking of MLS activity the median sale price in Palm Beach County was $495,000 as of mid-August. This is up 1.8% compared to a year ago. The average home is sold in 56 days. Sellers are getting 92% of their original asking price. There is 3.4 months of supply available, on the market. The situation still favors sellers. Only slightly. For buyers who have been waiting for rates to drop before making a move the important question is not “when will rates fall ” but “what do the current rates really mean for my monthly payment my ability to buy a home and the right time to act.” That’s what this week’s update is focusing on.
Per Momentum Realty’s tracking of MLS activity, mid-August 2026.
| Metric | Value | Context |
| Median sale price | $495,000 | Up 1.8% year-over-year |
| Typical time to contract | 56 days | Cooling from pandemic-era pace |
| Sale-to-list price ratio | ≈ 92% | Sellers still capturing most of asking |
| Months of supply | 3.4 months | Modestly favors sellers, not sharply |
| Active listings with a price cut | ≈ 23% | Room to negotiate on sitting inventory |
Where Rates Actually Stand Right Now
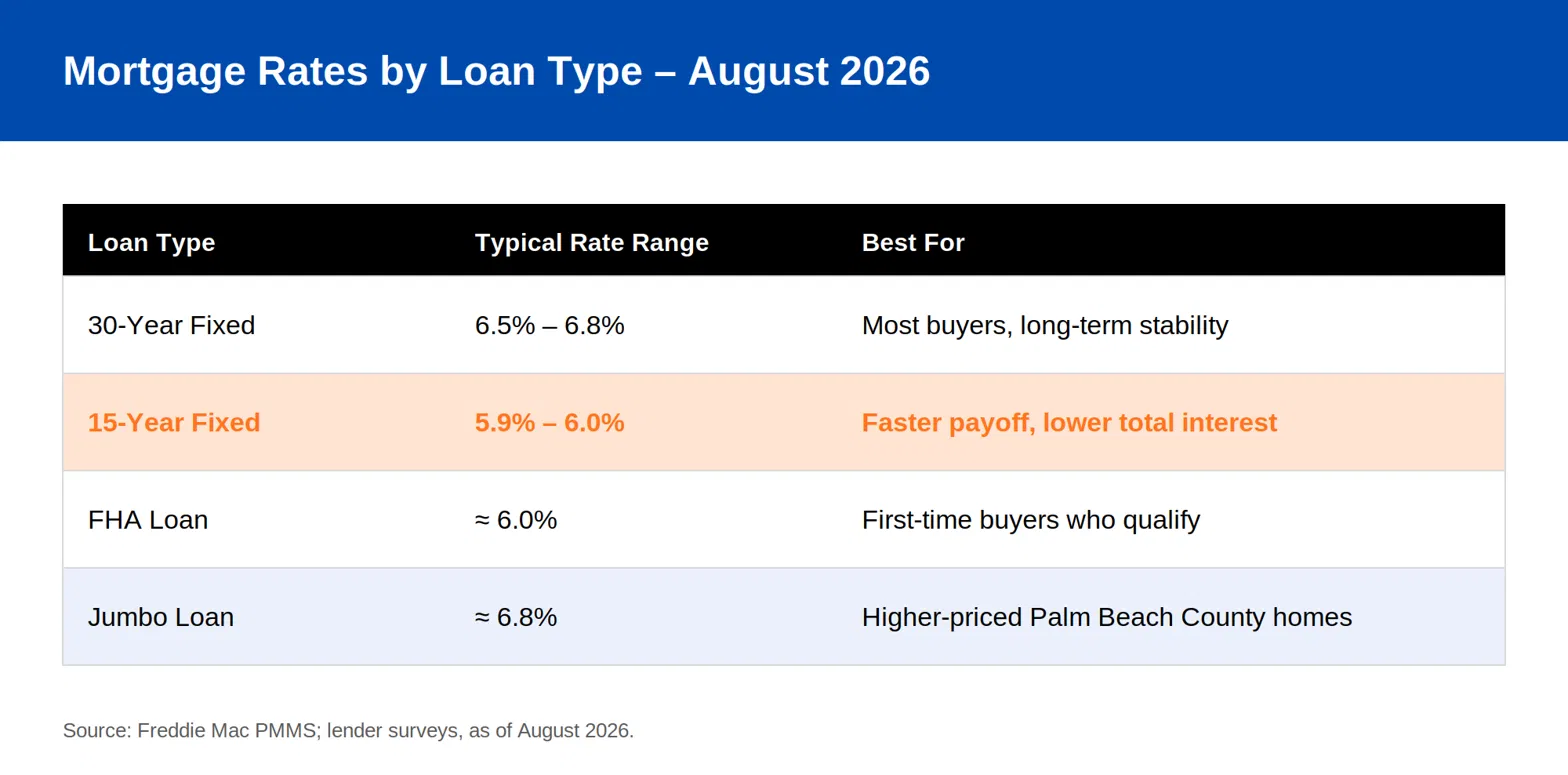
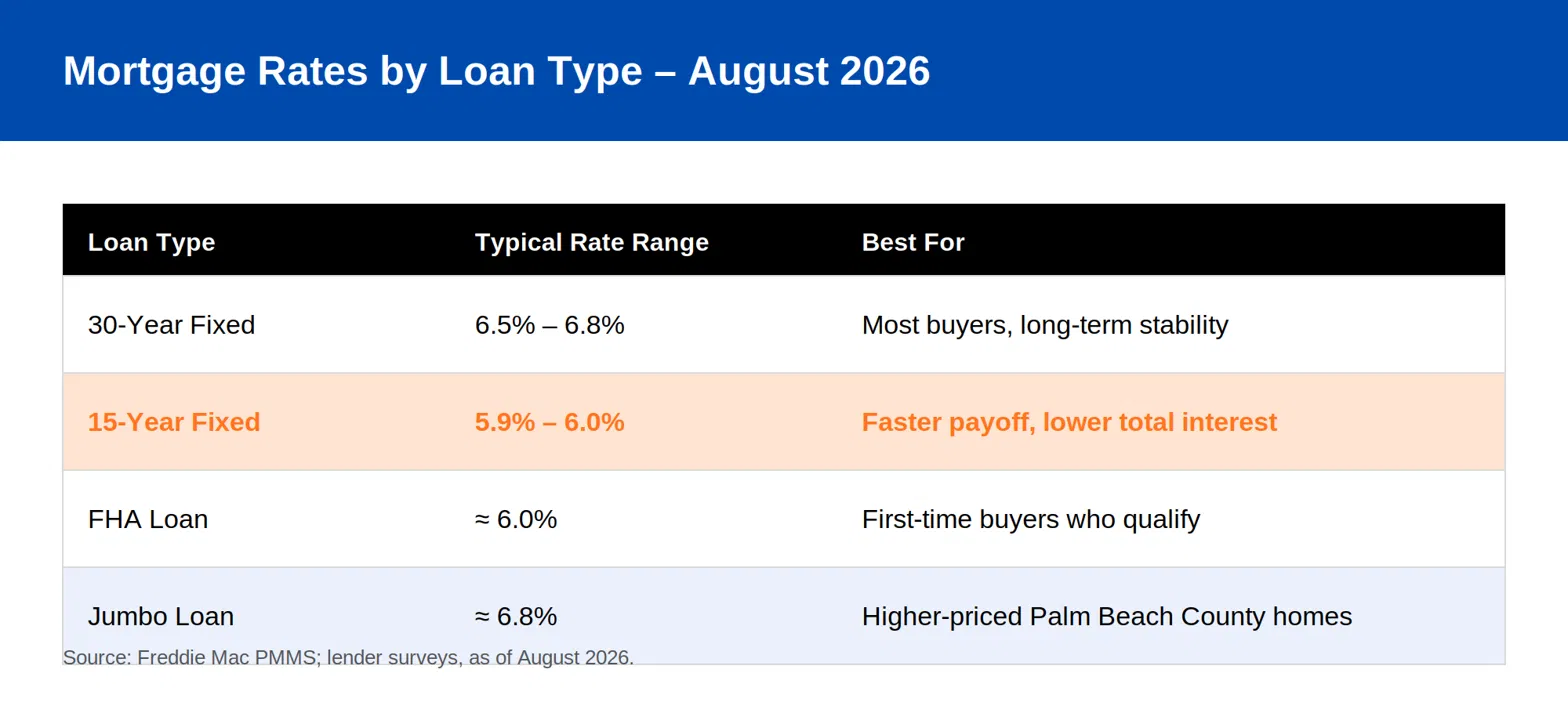
The current interest rates for mortgages are pretty high. The 30-year fixed-rate mortgage is around 6.5% to 6.8% now depending on who you ask and which lender you use. For example, Freddie Mac says it is at 6.65%. The 30-year fixed-rate mortgage rates are really important to know.
The 15-year fixed-rate mortgage is a little lower it is around 5.9% to 6.0%. Then there are FHA loans whichever around 6% these are still a good option for people buying a house for the first time if they qualify for them. FHA loans are a choice for first-time buyers who qualify.
Jumbo loans are another type of loan these are often used for houses like the ones in Palm Beach County. The interest rates for Jumbo loans are 6.8%. Jumbo loans are used for priced properties, like the ones, in Palm Beach County and they have higher interest rates.
The Federal Reserve has kept its benchmark rate the same through most of 2026 after a series of cuts in 2025. Forecasters at the Mortgage Bankers Association and, at Fannie Mae both say that the 30‑year mortgage rate will stay around six-point four percent to six-point five percent for the rest of the year unless there is an economic change. Daily changes have also been affected by events overseas. Those events have caused Treasury yields and mortgage rates to rise and fall in weeks.
What This Means for Your Monthly Payment
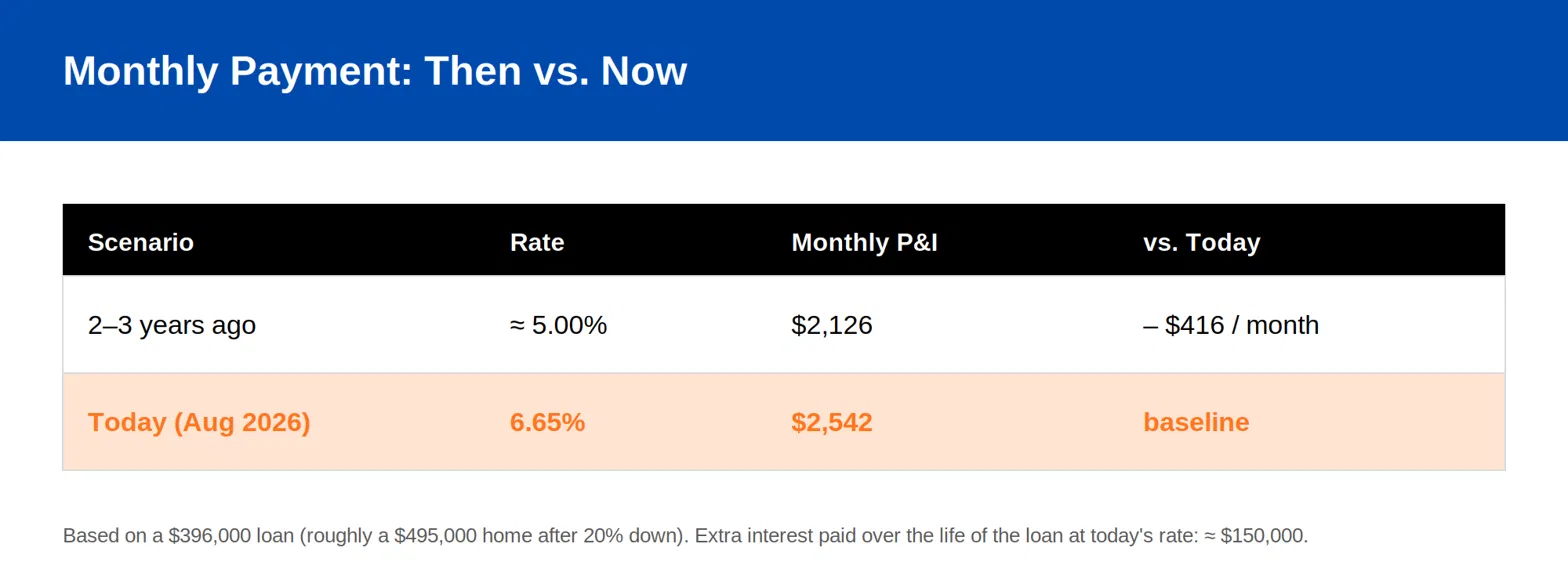
Math is really important when it comes to interest rates. Let us consider a loan of $396,000. This is approximately the amount a buyer would need to finance for a $495,000 home in Palm Beach County assuming they made a 20% down payment. If the interest rate is 6.65%, the monthly payment for principal and interest would be around $2,542.
A year ago, interest rates were around 5%. For the loan amount the monthly payment would have been about $2,126. That is a difference of around $416 every month. Over the life of the loan interest rates matter for math because a 6.65% interest rate on a $396,000 loan would cost close to $150,000 in interest compared to a 5% interest rate on a $396,000 loan. Math matters because interest rates have an impact, on how much you pay for a $396,000 loan.
That gap is real. That gap is the reason affordability, not price alone has become the main factor for many buyers. That gap also explains why rate movement receives much attention. Even a half-point shifts up or down can change what a buyer qualifies for or feels comfortable committing to, sometimes more than a change, in the home’s list price would.
Based on a $396,000 loan (roughly a $495,000 home after 20% down).
| Scenario | Rate | Monthly P&I | vs. Today |
| Two-three years ago | ≈ 5.00% | $2,126 | – $416 / month |
| Today (Aug 2026) | 6.65% | $2,542 | baseline |
Extra interest paid over the life of the loan at today’s rate: ≈ $150,000.
The Upside for Buyers: Less Competition, More Room to Negotiate
Higher interest rates have made it harder for buyers to get into the market compared to the excitement of a years ago. This has given power to buyers in a way that’s not obvious if you’re only looking at the numbers that get the most attention. On average sellers across the county are getting 92% of the price they asked for. Also 23% of the homes that are currently for sale have had their prices lowered at least once. There is opportunity to talk about price especially for homes that have been on the market for more, than a month or two.
Seller concessions are back on the table
Sellers are doing something to help buyers. They are paying for the buyers closing costs. Helping with a temporary rate buy down. This is of lowering the price of the house. A 1-0 or 2-1 buy down is when the seller pays to lower the buyers interest rate for the year or two of the loan. This can really help the buyer because it makes their payments lower for the few years. It is an idea to ask about this when you make an offer to buy a house in this market. The temporary rate buy down can make a difference, for the buyer.
Rate locks and float-downs deserve attention
Buyers who are under contract should talk to their lender about float-down options for their mortgage loan. This is because the interest rates are still changing every week. If the interest rates go down before the loan is finalized the float-down option can help the buyers get the interest rate. It does not cost much to ask about this option. The buyers can really benefit from this option when they have a 30-year mortgage loan. The mortgage loan is for a time so a small change in the interest rate can make a big difference. Buyers should ask their lender about float-down options, for their mortgage loan.
For Sellers: Rate-Sensitive Buyers Are Still Buying, Just Differently
Sellers should not think that when interest rates go up buyers will just disappear. Instead they should understand that buyers will be more careful about what they buy. They will think more about how much they have to pay each month. They will try to negotiate a better price. If a home is priced correctly looks good and the seller is clear about how it will really cost each month it will sell faster. This is especially true if the seller includes any deals they are offering. It is an idea for sellers to work with a real estate agent who can explain to buyers what their monthly payments will really be, not just the price of the house. This can make a difference in whether a buyer makes an offer on a home or just looks at it and does nothing. Homes that are priced right and marketed well including the monthly cost of homes tend to sell faster, then homes that are priced based on what similar homes sold for last year.
For Investors: Cash Still Rules in Palm Beach County
Interest rate changes hit people who need loans harder than they hit cash buyers. Cash buyers still make up a part of the market in Palm Beach County. I see many of these cash buyers are people moving here from the Northeast and Midwest. When investors use loans to buy properties the current interest rates make the math for monthly cash flow much harder. Because of these interest rates more investors are looking for value-add opportunities. Many investors are also looking at markets, outside the most expensive coastal areas. In those areas the entry prices and the cost of loans make more sense.
What to Watch Over the Rest of 2026
The direction of rates for the rest of the year will depend mostly on inflation data and on how the Federal Reserve interprets that data at each coming meeting well as on how global events that influence oil prices and Treasury yields unfold. Most forecasters do not expect the rate to return to the 5 percent range this year. That means the realistic plan, for buyers is not to wait for rate to fall but to buy the home that fits your budget now and to refinance later if rate becomes better.
Final Takeaways for Buyers, Sellers, and Investors
- Buyers: Do not let the headlines about interest rates stop you from buying a house. You have a lot of power to negotiate now. Ask the seller if they can help you with the costs. You can also ask about lowering the interest rate. Do not think that you are stuck with the interest rate. The buyers have power to negotiate than they have had in a long time.
- Sellers: When you are selling your house think about the interest rates. Do not think about what houses were selling for year. Be prepared to help the buyer with their payments. This can be better for you than lowering the price of the house. The seller should price the house based on the interest rates.
- Investors: When you are thinking about buying a house to rent out be careful with your numbers. Use the interest rates to figure out if it is a good deal. Look for houses in areas and think about what types of houses will still make you money. The investors should run the numbers, on financed deals at today’s interest rates.
Interest rates will continue to change. No one can predict them exactly. What is more important is knowing what today’s rate means for your purchase, your particular budget and your particular timeline. It is also important to have a plan that works no matter which way the next Federal Reserve meeting goes.
So, what does this mean for your step? Speak with Alan Siegel and the team at ET-OP Realty Group. They can explain what current rates really mean for your ability to buy connect you with lenders who provide options, like buy downs and create a plan that fits your goals and your neighborhood.
About the Author
Alan Siegel is the Founder and Principal of ET-OP Realty Group. He helps people buy, sell and invest in homes across Palm Beach County. Alan believes that navigating today’s market requires a plan, real market knowledge and a partner you can trust. He doesn’t measure luxury by price tag alone; he measures it by the quality of service a client receives from start to finish.
Whether you’re buying your home selling a high-end property growing an investment portfolio or looking for a place to land for a season Alan is there to help. He draws on deep market knowledge and current data to help clients understand home value and negotiate with confidence and he’s known for marketing homes in a way that gets them the attention they deserve.
Alan wants his clients to make decisions with confidence, not anxiety. He communicates clearly gives advice and stays attentive to the details from the very first conversation through closing day. That commitment is the foundation of ET-OP Realty Group, whose motto’s Optimistic About Every Move. Alan and his team are always looking for the opportunity, in a shifting market. They put clients first whether they’re moving up downsizing, investing or buying for the very first time.